No Result
View All Result
  • Private Data
  • Membership options
  • Login
  • COUNTRY
    • ITALY
    • IBERIA
    • FRANCE
    • UK&IRELAND
    • BENELUX
    • DACH
    • SCANDINAVIA&BALTICS
  • PRIVATE EQUITY
  • VENTURE CAPITAL
  • PRIVATE DEBT
  • DISTRESSED ASSETS
  • REAL ESTATE
  • FINTECH
  • GREEN
  • PREMIUM
    • ItaHubHOT
      • ItaHub Legal
      • ItaHub Tax
      • ItaHub Trend
    • REPORT
    • INSIGHT VIEW
    • Private Data
Subscribe
  • COUNTRY
    • ITALY
    • IBERIA
    • FRANCE
    • UK&IRELAND
    • BENELUX
    • DACH
    • SCANDINAVIA&BALTICS
  • PRIVATE EQUITY
  • VENTURE CAPITAL
  • PRIVATE DEBT
  • DISTRESSED ASSETS
  • REAL ESTATE
  • FINTECH
  • GREEN
  • PREMIUM
    • ItaHubHOT
      • ItaHub Legal
      • ItaHub Tax
      • ItaHub Trend
    • REPORT
    • INSIGHT VIEW
    • Private Data
Home COUNTRY ITALY

Rating agencies give their investment grade vote to Esselunga, waiting for the bond

Bebeezby Bebeez
October 10, 2017
Reading Time: 2 mins read
in ITALY, PRIVATE DEBT
Share on FacebookShare on Twitter

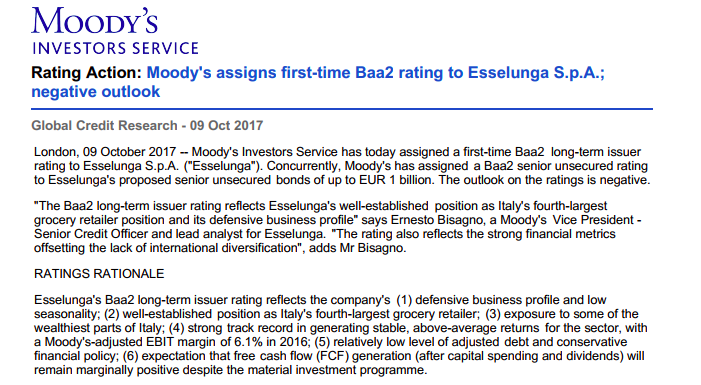
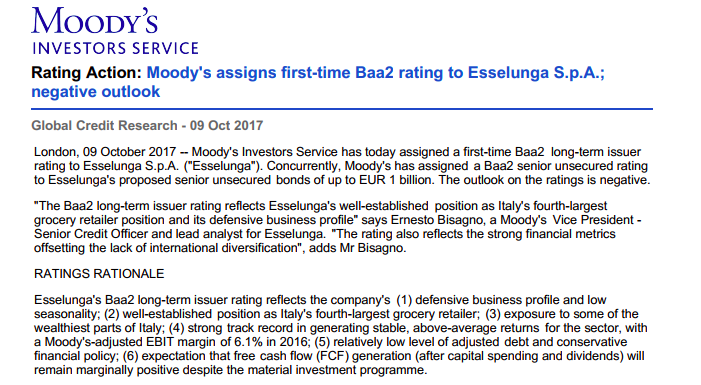
EsselungaMoody’s assigned a Baa2 long-term corporate rating to Esselunga spa and its coming senior unsecured bond.On the same side was also Standard&Poor’s who assigned a preliminary BBB- rating to the group with a stable outlook.

The Italian supermarket chain is actually issuing its first bond for as much a one billion euros in order to partly refinance a 1.5 billion euros loan it obtained last July by a pool of banks (Citi, Mediobanca, Unicredit, Intesa Sanpaolo and then Banco Bpm and Bnp Paribas). The loan was necessary to finance a shareholders re-organization of the group controlled by the Caprotti family in view of the listing of Esselunga at the Italian Stock Exchange in 18-24 months. 

Esselunga reached 7.54 billion euros in revenues in 2016 with 661 millions in ebitda. Moody’s said that the rating reflects the company’s (1) defensive business profile and low seasonality; (2) well-established position as Italy’s fourth-largest grocery retailer; (3) exposure to some of the wealthiest parts of Italy; (4) strong track record in generating stable, above-average returns for the sector, with a Moody’s-adjusted ebit margin of 6.1% in 2016; (5) relatively low level of adjusted debt and conservative financial policy; (6) expectation that free cash flow (FCF) generation (after capital spending and dividends) will remain marginally positive despite the material investment programme. The rating also reflects the company’s (1) lack of international diversification and hence reliance on the economic conditions in Italy, although Moody’s notes the company’s resilient performance during the financial crisis; (2) relatively smaller size and higher geographical concentration than other rated European retailers.

Moody’s also says that leverage (Moody’s adjusted gross debt to ebitda) at December 2017 to be 2.3x. The calculation includes around 1.3 billion euros of debt of which almost 900 millions funding the acquisition of the 67.5% stake in Villata Partecipazioni spa and 417 million euros of adjustments for operating leases and pensions. In addition, the rating agency notes the existence of 300 millions of debt at the level of the holding company Supermarkets Italiani spa and the significant minority stake of 32.5% in Villata Partecipazioni. While the 300 million euros debt is not factored in Moody’s credit metrics, the holding company Supermarkets largely relies on dividend payments from Esselunga to service the debt.

Finally, Moody’s expects FCF generation to be broadly neutral in 2018, owing to discretionary capex plan and working capital needs due to changing value-added tax payables, and to improve in 2019-20 at  50 -100 million euros each year. As a result, Moody’s expects leverage to decline marginally towards 2.2x by 2019, with the decline driven by a combination of higher ebitda and stable gross debt. On a reported net debt to ebitda calculation, that would be equal to 1.3x in 2019, down to 1.1x in 2020, within the company’s targets to maintain reported net leverage below 1.5x.

Gateways to Italy

Gateways to Italy – Offer your services to funds and investors willing to explore opportunities in Italy. Become a partner!

Gateways to Italy – Offer your services to funds and investors willing to explore opportunities in Italy. Become a partner!

by Partner
June 6, 2023

Sign up to our newsletter

SIGN UP

Related Posts

Private equity invests billions in proprietary data. But how many funds really know how to turn it into a competitive advantage?
BENELUX

Private equity invests billions in proprietary data. But how many funds really know how to turn it into a competitive advantage?

November 2, 2026
PRIVATE DEBT

Virgin Media O2 to cut thousands of jobs in cost-savings push – report

November 2, 2026
BeBeez Carve-Outs Focus #5 – From Business Unit to Standalone Company: Cultural and Managerial Transformation
BENELUX

BeBeez Carve-Outs Focus #9 – From delegated management to active management: how to manage a perpetual compounder portfolio

November 2, 2026

ItaHub

Crypto-assets supervision rules in Italy, Banca d’Italia will supervise payment systems and Consob on market abuse

Crypto-assets supervision rules in Italy, Banca d’Italia will supervise payment systems and Consob on market abuse

November 4, 2024
Italy’s SMEs export toward 260 bn euros in 2025

Italy’s SMEs export toward 260 bn euros in 2025

September 9, 2024
With two months to go before the NPL Directive, in Italy the securitization rebus is still to be unraveled

With two months to go before the NPL Directive, in Italy the securitization rebus is still to be unraveled

April 23, 2024
EU’s AI Act, like previous rules on technology,  looks more defensive than investment-oriented

EU’s AI Act, like previous rules on technology, looks more defensive than investment-oriented

January 9, 2024

Co-sponsors

Premium

Private equity: 476 deals in Italy in the first nine months of 2026 and over €25 billion of stakes changing hands. The BeBeez report

Private equity: 476 deals in Italy in the first nine months of 2026 and over €25 billion of stakes changing hands. The BeBeez report

October 19, 2026

Western Balkans attract 50 billion euros for the Croatian data centre and 3.2 billion for Montenegro – Kinstellar report

September 29, 2026
The energy transition is now an asset class for private markets

The energy transition is now an asset class for private markets

June 25, 2026
The AI halves the time for creating value – FTI Consulting Private Equity Value Creation Index 2026

The AI halves the time for creating value – FTI Consulting Private Equity Value Creation Index 2026

June 10, 2026
Next Post

International PET leader Mossi Ghisolfi group to sell its biofuel business in Italy

Four bidders selected in the short list for Italy's asset manager Quadrivio sgr

EdiBeez srl

C.so Italia 22 - 20122 - Milano
C.F. | P.IVA 09375120962
Aut. Trib. Milano n. 102
del 3 aprile 2013

COUNTRY

Italy
Iberia
France
UK&Ireland
Benelux
DACH
Scandinavia&Baltics

CATEGORY

Private Equity
Venture Capital
Private Debt
Distressed Assets
Real Estate
Fintech
Green

PREMIUM

ItaHUB
Legal
Tax
Trend
Report
Insight view

WHO WE ARE

About Us
Media Partnerships
Contact

INFORMATION

Privacy Policy
Terms&Conditions
Cookie Police

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
No Result
View All Result
  • COUNTRY
    • ITALY
    • IBERIA
    • FRANCE
    • UK&IRELAND
    • BENELUX
    • DACH
    • SCANDINAVIA&BALTICS
  • PRIVATE EQUITY
  • VENTURE CAPITAL
  • PRIVATE DEBT
  • DISTRESSED ASSETS
  • REAL ESTATE
  • FINTECH
  • GREEN
  • PREMIUM
    • ItaHub
      • ItaHub Legal
      • ItaHub Tax
      • ItaHub Trend
    • REPORT
    • INSIGHT VIEW
    • Private Data
Subscribe
  • Login
  • Cart